Hyperliquidexchange funding rates
Hyperliquid settles perpetual funding every hour between long and short position holders. Positive funding makes longs pay shorts; negative funding makes shorts pay longs. The amount depends on position notional and the applicable hourly rate. Standard crypto perpetuals, HIP-3 perpetuals, and hyperps have different premium rules or reference inputs. Estimating a payment leaves the position unchanged; reducing or closing it changes future funding exposure only when the closing trade fills.
Reading the rate before taking exposure
Funding encourages perpetual prices to stay near their reference prices. It is separate from execution fees charged on trades, and Hyperliquid collects no fee on the funding transfers themselves.
The standard funding formula expresses a rate on an eight-hour basis. Hyperliquid applies one eighth of that computed rate at each hourly settlement. The fixed interest component is 0.01% per eight hours, equivalent to 0.00125% per hour, and the formula combines it with a variable premium. That fixed component alone does not determine the total rate or which side receives payment.
How the hourly payment is calculated
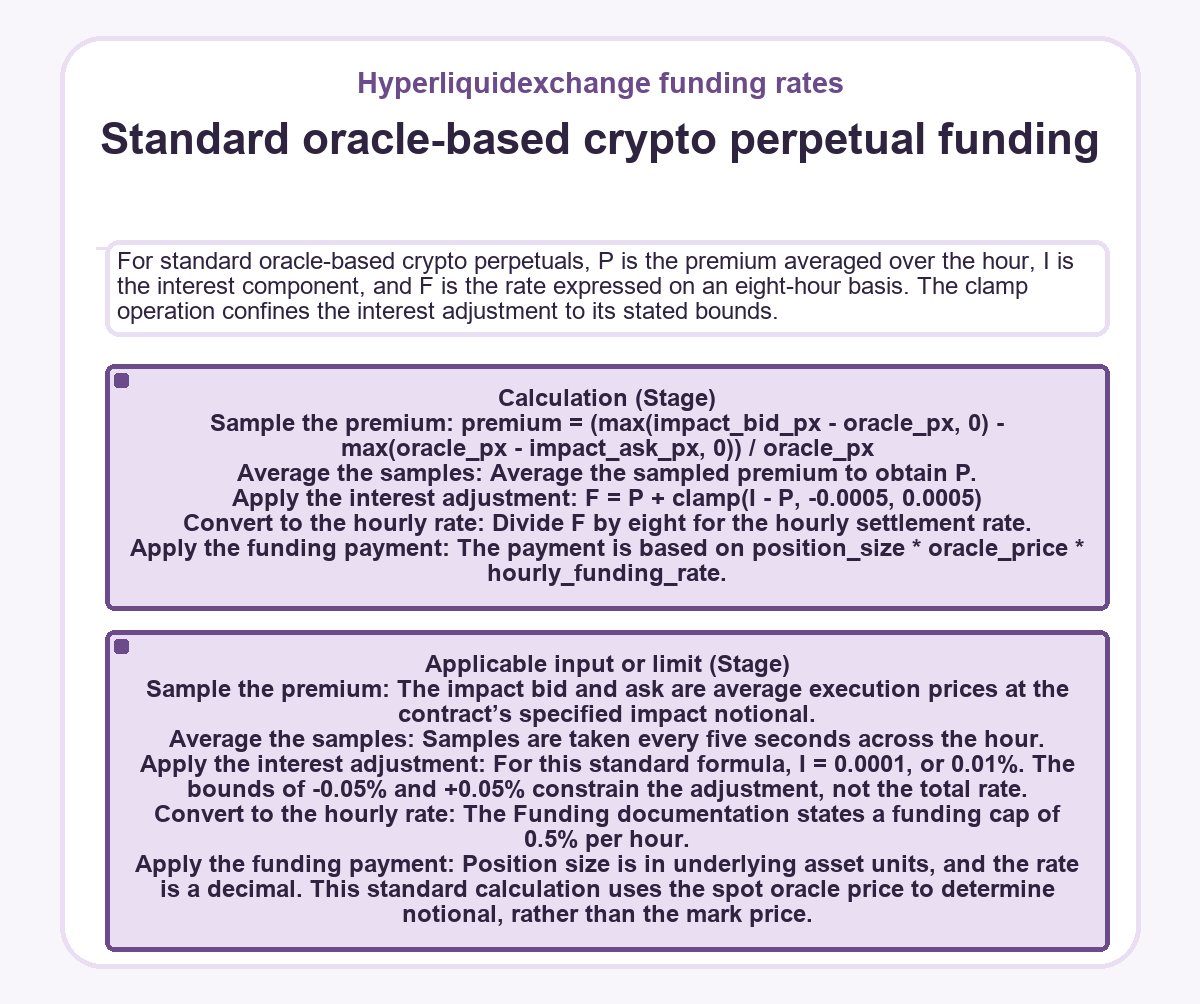
For standard oracle-based crypto perpetuals,
P
is the premium averaged over the hour,
I
is the interest component, and
F
is the rate expressed on an eight-hour basis. The
clamp
operation confines the interest adjustment to its stated bounds.
| Stage | Calculation | Applicable input or limit |
|---|---|---|
| Sample the premium |
premium = (max(impact_bid_px - oracle_px, 0) - max(oracle_px - impact_ask_px, 0)) / oracle_px
|
The impact bid and ask are average execution prices at the contract’s specified impact notional. |
| Average the samples |
Average the sampled premium to obtain
P
.
|
Samples are taken every five seconds across the hour. |
| Apply the interest adjustment |
F = P + clamp(I - P, -0.0005, 0.0005)
|
For this standard formula,
I = 0.0001
, or 0.01%. The bounds of -0.05% and +0.05% constrain the adjustment, not the total rate.
|
| Convert to the hourly rate |
Divide
F
by eight for the hourly settlement rate.
|
The Funding documentation states a funding cap of 0.5% per hour. |
| Apply the funding payment |
The payment is based on
position_size * oracle_price * hourly_funding_rate
.
|
Position size is in underlying asset units, and the rate is a decimal. This standard calculation uses the spot oracle price to determine notional, rather than the mark price. |
Position notional and margin have different roles
Collateral alone is insufficient to estimate funding. With position size, oracle price, and hourly rate held constant, changing the amount of margin does not change the funding amount. A larger absolute position size produces a proportionally larger debit or credit at the same nonzero rate and oracle price. To reduce a long, use a reduce-only sell; to reduce a short, use a reduce-only buy. A closing order changes exposure only to the extent that it fills. A full close before the next settlement ends further funding on that position while it remains closed; earlier funding payments remain recorded.
A forecast covering several hours depends on the position sizes and rates for those later settlements. Extending one observed hourly rate across the entire holding period gives a conditional estimate because the premium is sampled again each hour.
HIP-3 and hyperps require their own inputs
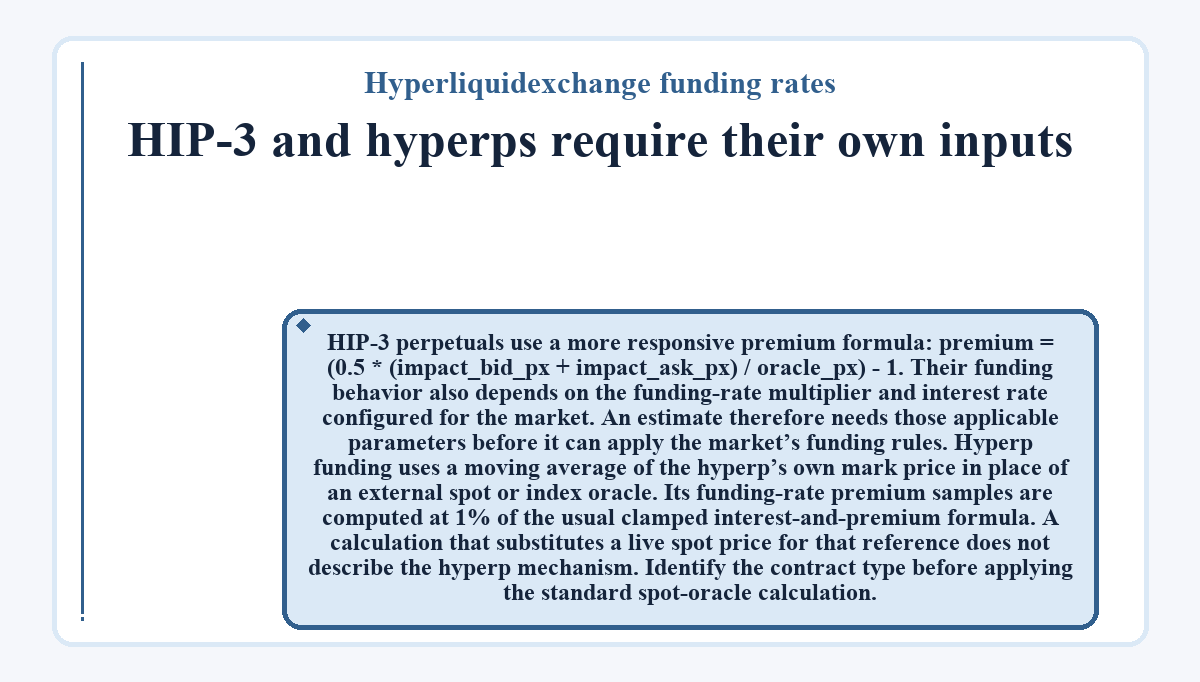
HIP-3 perpetuals use a more responsive premium formula:
premium = (0.5 * (impact_bid_px + impact_ask_px) / oracle_px) - 1
. Their funding behavior also depends on the funding-rate multiplier and interest rate configured for the market. An estimate therefore needs those applicable parameters before it can apply the market’s funding rules.
Hyperp funding uses a moving average of the hyperp’s own mark price in place of an external spot or index oracle. Its funding-rate premium samples are computed at 1% of the usual clamped interest-and-premium formula. A calculation that substitutes a live spot price for that reference does not describe the hyperp mechanism. Identify the contract type before applying the standard spot-oracle calculation.
Separate an estimate from a recorded payment
A prospective calculation estimates funding under its stated inputs. Hyperliquid’s
userFundings subscription
supplies a funding snapshot followed by updates on the hour. Funding entries include
time
,
coin
,
usdc
,
szi
, and
fundingRate
, identifying the recorded amount and its position context.
Trade fees appear in fill records, while
userNonFundingLedgerUpdates
excludes
funding payments. Funding entries are the relevant records for reconciling funding costs or credits.